The weighted distribution rate of SCPI for the first half of 2026 stands at 2.30%, nearly stable compared to the 2.29% of the first half of 2025. This overall figure masks a reality that semi-annual reports soften: more than half of the SCPI have lowered their advance payments in 2026.
The apparent stability of the average relies on a minority of vehicles that outperform, pulling the distribution rate upward while the majority compress their distributed income.
Dispersion of SCPI Advances 2026: The Average is No Longer Enough
Reading the average distribution rate as a health indicator for the SCPI market loses relevance as 53% of funds have reduced their advance payments since January 2026. This concentration phenomenon, where a handful of SCPI capture most of the displayed performance, is not new, but its scale in 2026 warrants granular examination.
We observe that the most successful SCPI, often the youngest and most geographically diversified, maintain or increase their distributions. Their assets, acquired at post-correction prices, generate rental yields higher than those of historical vehicles whose real estate stock was built at the peak of the cycle.
For holders of shares in older SCPI, the question is not whether the average market yield is increasing. It is to check whether their specific SCPI is among the half that distributes less. The ASPIM/IEIF data published in August 2026 confirms this reading: analyzing the SCPI yield in France in August 2026 requires going beyond the weighted average to examine the actual distribution, fund by fund.
SCPI Collection France 2026: A Return to the 2018 Regime, Not a Surge
The recovery of net collection in the first half of 2026 fuels an optimistic narrative in wealth management media. We recommend placing it in its historical context. The current pace corresponds more to the volumes observed around 2018 than to the euphoric phase of 2020-2022.
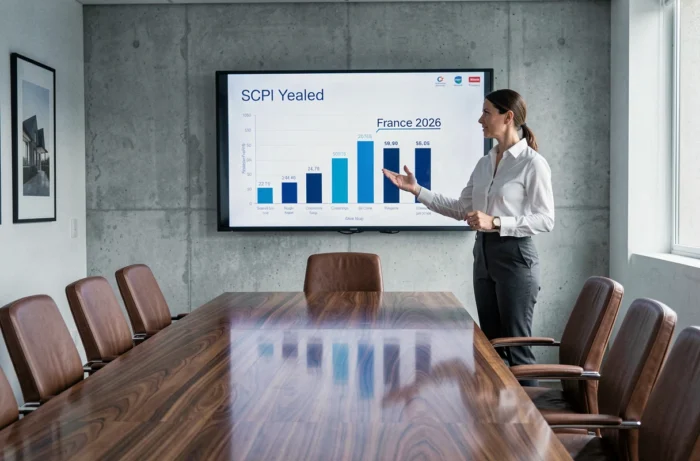
10 SCPI concentrate about 70% of the semi-annual collection, according to data relayed by Investir. This polarization means that the majority of vehicles struggle to raise fresh capital, which directly affects their ability to acquire new assets and smooth their yields.
Three factors explain this concentration:
- Pan-European diversified SCPI attract flows because they offer reduced taxation for French residents, through tax treaties on foreign rental income.
- Recent vehicles, without pre-crisis real estate stock, show stable or rising share prices, which reassures subscribers burned by the declines in reconstitution values of 2023-2024.
- Thematic SCPI (logistics, health) benefit from a strong sector narrative, even if their volumes remain modest compared to office giants.
Interest Rates and Real Estate Asset Prices: The Dual Signal to Read in August
The 10-year OAT, close to 4%, compresses the risk premium of SCPI. In 2025, the average distribution rate was 4.91%. The gap with the sovereign risk-free rate has thus narrowed to less than one point, a historically low level for this asset class.
A risk premium of less than one point raises questions about the remuneration of real estate risk. The limited liquidity of shares, the enjoyment delays, and the subscription fees weigh on the effective net yield. When the euro fund or the sovereign bond offers a comparable yield/liquidity pair, the argument for “real estate investment” loses its strength.
In the underlying asset market, the situation remains mixed. Offices, which still constitute the majority of the assets of French SCPI, are experiencing structurally weakened demand due to telecommuting and the geographical reorganization of companies. Valuations are stagnating or declining moderately, which weighs on the share prices of exposed vehicles.
Tertiary Real Estate: A Differentiated Recovery by Segment
City center retail and last-mile logistics show occupancy rates higher than those of peripheral office spaces. SCPI positioned in these segments more easily maintain their distributions.
We find that diversified SCPI in Europe outperform 100% France vehicles in the first half of 2026, driven by more dynamic rental markets in certain Nordic and Iberian metropolises. For an investor focused on France, this data does not disqualify domestic SCPI, but it imposes the need to verify the financial occupancy rate and the rental quality of the portfolio, rather than relying solely on the displayed distribution rate.
SCPI Yield and ISR Label: A Management Criterion, Not a Performance One
The ISR real estate label, adopted by an increasing number of SCPI, modifies the selection criteria for assets in the portfolio. Its impact on the distributed yield remains ambiguous at this stage.
The energy improvement works required to maintain or obtain the label generate investment expenses that reduce the distributable result in the short term. Over a horizon of five to ten years, these expenses can support the market value of the assets and their rental attractiveness. But as of August 2026, the ISR label does not guarantee either a superior yield or lower volatility in share price.
For the saver, the ISR label remains an indicator of management quality and transparency, not a selection criterion based on performance. Labeled SCPI publish more extra-financial data, which facilitates analysis, without promising a surplus in distribution.
What to Monitor Specifically Until the End of 2026
The second half will bring several determining elements to refine the analysis of SCPI yield in France:
- The year-end valuation, which will condition any potential adjustments in share prices for office SCPI.
- The evolution of net collection in the third quarter, an advanced indicator of investor confidence and the investment capacity of managers.
- The positioning of the ECB on key rates, which will influence the cost of real estate credit and, by extension, the valuations of tertiary assets.
- The publication of third-quarter advances, the only reliable indicator to distinguish SCPI that meet their distribution objectives from those that deviate from them.
The SCPI market in 2026 cannot be summarized by a reassuring average distribution rate. The dispersion of performances, the concentration of collection, and the compression of the risk premium shape an environment where individual selection of vehicles takes precedence over any logic of passive allocation. Each line in the portfolio deserves updated analysis, asset by asset.